
India VIX: what the market’s ‘fear gauge’ is really telling you
When markets panic, one number spikes — India VIX. What the volatility index measures, what its levels mean, and why it's called the fear gauge.

How a stock's price is actually set
Nobody "fixes" a share price — it's decided every second by buyers and sellers. How the order book really works, in plain words.

Large-cap, mid-cap, small-cap: what they mean for you
These labels decide how safe or risky a stock is. What market cap really means, the exact 2026 cut-offs, and how to use them.

What moves the market: rates, inflation, crude and the rupee
Four big forces quietly push the whole market up or down. Interest rates, inflation, oil and the rupee — explained with 2026 numbers.

Upper and lower circuits, ASM and GSM: why a stock suddenly ‘freezes’
Sometimes a stock can't be bought or sold at any price — it's hit a circuit. Circuit limits, and the ASM and GSM surveillance lists, explained — and why they protect you.

What is GIFT Nifty? The pre-market signal that hints at tomorrow's market
Before the market opens, everyone watches GIFT Nifty for a hint of the day ahead. What GIFT Nifty is in simple words, how it replaced SGX Nifty, and why it is only a hint.

FII and DII explained: what "FII buying today" and "FII selling" really mean
Headlines shout "FII buying today" or "FII selling". In simple words: who FIIs and DIIs are, why their money moves the market, and why you should not trade on one day's figure.

52-week high and 52-week low: what these numbers really tell you
The 52-week high and low appear on every stock page. In simple words: what they mean, why a low is not automatically "cheap", and how to use them sensibly.

The NIFTY Is Down 14%. But Is the Market Really Down?
NIFTY 50 fell 14% in 2026, but one-third of analysed stocks gained over 10%. Explore stock-level performance, market dispersion and momentum.

Sensex vs Nifty: what a stock index actually is (and the Nifty 100, Midcap 150 and Smallcap 250)
The Sensex and Nifty are quoted every day — but what do they really measure? What an index is, how the Sensex and Nifty differ, and the full Nifty family explained.
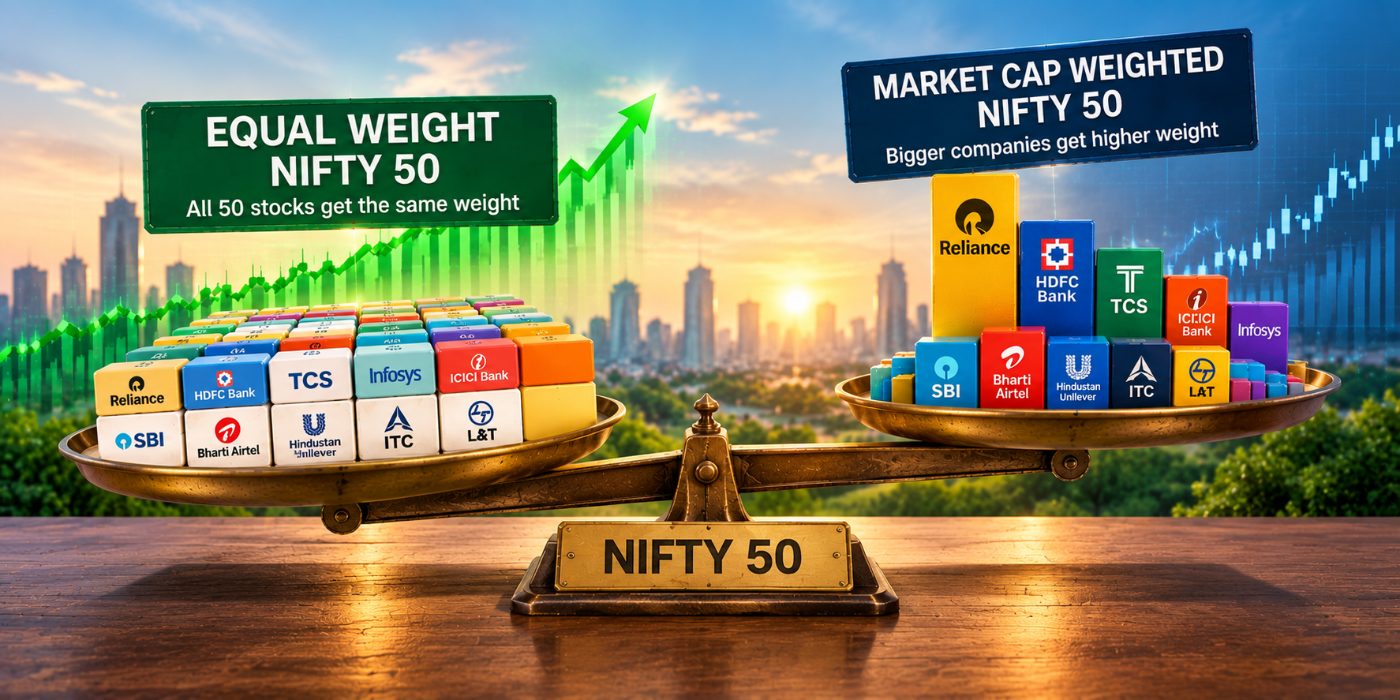
Equal-Weighted vs Market-Cap-Weighted NIFTY 50: Which Has Performed Better?
Discover why Equal Weight Nifty 50 outpaces traditional Market-Cap weighting. Read our comprehensive YoY return and drawdown analysis to rethink index investing.

21 Crore Demat Accounts — But How Many Indians Are Actually Investing?
India has crossed 21 crore demat accounts. Sounds like a massive investing revolution. But SEBI's data reveals a more nuanced story: accounts are growing much faster than active, sustained participation. So, are Indians really becoming long-term investors—or are we simply opening more accounts?

₹6.9 Lakh Crore Entered India’s Securities Market — But Where Did the Money Actually Go?
Indian households channelled ₹6.91 lakh crore into the securities market in FY25, almost twice the FY24 figure. But here's the interesting part: most of this money did not go directly into stocks.